Indian investors are broadening their Dubai property strategies beyond residential assets, with offices, retail and industrial-logistics attracting greater attention. Aayush Puri, CEO of ANAROCK Middle East, discusses what is driving the shift, how the Indian buyer is evolving and which commercial micro-markets could shape the next phase.
September 30, 2026 | Tripti Mehta | UAE | Real Estate | 5 Min Read
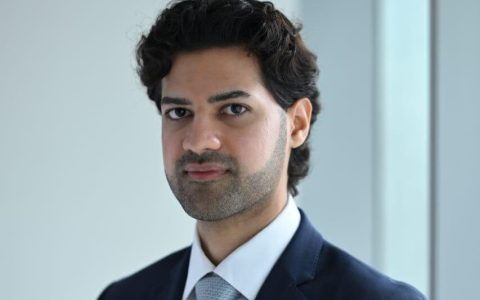
Image Courtesy: ANAROCK Middle East
Q: What is prompting Indian investors to look at commercial assets, and how much is driven by rental yields versus building a UAE business footprint?
Higher rental yields are not the sole reason why Indian investors are looking at commercial real estate alongside residential property. Recurring income and longer leases, along with the opportunity for international portfolio diversification, also play a role.
Dubai’s business-friendly environment and the quality of life it offers further strengthen this proposition, especially for those who eventually want to relocate here and leverage Dubai’s access to regional and global markets to establish or expand their business.
By the end of H1 2026, the Dubai Chamber of Commerce had 85,841 Indian companies as active members, up 15% YoY, which shows the depth of the presence of Indian businesses in the city. This business presence is also relevant in the context of demand for commercial space.
According to ANAROCK, office transaction volumes in Dubai increased 38% YoY in H1 2026, and retail transaction volumes rose 56%.
Q: Which commercial segments are drawing the most Indian interest, and which have the strongest three-to-five-year case?
Indian investors are considering offices, retail, and industrial-logistics, but the investment case differs across these segments.
The demand for quality workspace and tight availability in established business districts is driving office demand. Retail is also seeing strong transaction activity, although its performance remains closely tied to location, catchment, and tenant mix.
Given Dubai’s role as a regional trade, manufacturing and distribution hub, and the consequent demand for warehousing and supply-chain infrastructure, industrial and logistics have considerable potential over the longer term.
Hospitality presents a mixed picture as of now. The sector entered 2026 on a strong footing, but regional geopolitical tensions and disruptions to international air travel affected its performance. However, occupancy has recovered sharply. In August 2026, Dubai hotel occupancy rose to 66% from just 36% in March 2026.
So, that makes it a sector that isn’t a top investment pick right now, but whose investment prospects are expected to improve further as the geopolitical situation gradually settles.
Over the next three to five years, I would particularly watch Grade A offices and industrial-logistics. Both offer exposure to business activity that extends beyond the property cycle. In addition, the diversity of occupiers and use cases can create opportunities across different ticket sizes and asset formats.
Q: How prepared are Indian residential investors for commercial property’s different rulebook?
Preparedness depends on the investor profile. Those with a business background, HNIs, and family offices tend to have a better understanding of commercial asset underwriting. However, for investors moving into commercial real estate from a residential mindset, there is a learning curve.
In Dubai, vacancy, tenant profile, management quality, service charges, and resale liquidity can vary from one building to another. This makes commercial decision-making capability as important as the availability of capital.
Therefore, advisory becomes important for investors entering the commercial real estate market in Dubai, as they need to assess not just the asset, but the tenant, lease, micro-market, competing supply, and exit potential together to minimise risks and ensure that the asset aligns with their operational and business objectives.
Q: Who is driving this shift, and how has the Indian buyer changed?
Because of higher ticket sizes and longer holding periods, commercial assets require greater financial capacity on the investor’s end. That is why HNIs and family offices naturally have a more prominent role in Dubai’s commercial real estate.
However, many senior professionals, entrepreneurs, and mid-sized business owners are also eyeing commercial properties in Dubai for investment and portfolio diversification.
Also, a notable change that I have observed in the last two years is increasing buyer sophistication.
Location and capital appreciation are no longer the only factors buyers consider when leasing/buying commercial property. Rental logic, asset quality, the business ecosystem, and exit visibility are now being assessed more closely.
Overall, I see two parallel trends in the market. First, larger, professionally managed capital is moving towards commercial assets. Second, a broader Indian investor base is building Dubai exposure through smaller-ticket, yield-led opportunities.
Q: How can commercial property become more accessible, and what comes next for Indian investors?
Strata offices, REITs, and fractional ownership have made commercial real estate accessible to a wider investor base.
Going forward, developers will need to focus on smaller, efficiently managed commercial units, flexible floorplates, transparent leasing economics, and professional asset management to channel Indian capital into this segment. Savills’ Q1 2026 data shows that 97% of office deals were for spaces of 3,000 sq ft or less, reinforcing the demand for smaller formats.
Simultaneously, regulators should prioritise transparency, governance and liquidity. The Dubai Land Department took a step in this direction in February 2026 by enabling secondary-market resale for tokenised real estate.
In the near term, the Indian investor’s Dubai playbook will shift from property ownership to property exposure. In other words, investors will not only decide what to buy, but also which structure to use to gain exposure to Dubai commercial real estate.
Q: Which emerging Dubai commercial micro-markets should Indian investors watch?
In my view, the Dubai South-Expo corridor and the Jebel Ali–DIP industrial belt are the areas with good prospects. Dubai South and Expo are emerging office submarkets, particularly for larger occupier requirements.
In industrial and logistics, Dubai South recorded the strongest rental growth among Dubai’s industrial submarkets in H1 2026, with rents rising 22% YoY.
JAFZA, within the Jebel Ali industrial and logistics hub, attracted AED 854 million in new investments in the first four months of 2026, across sectors such as manufacturing, logistics, and healthcare.
Infrastructure, connectivity, occupier demand, supply pipeline, and asset quality are a few factors that shape the attractiveness of these locations.